
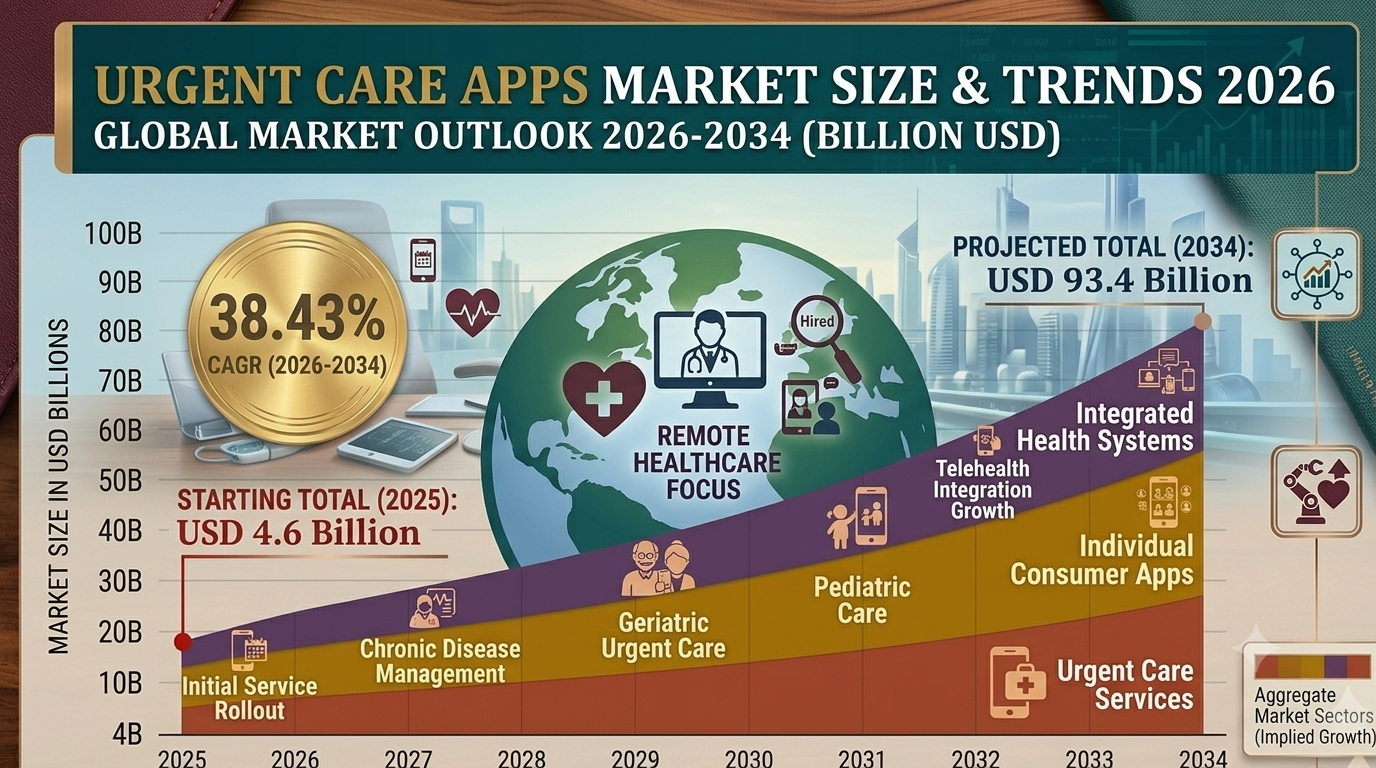
The urgent care apps market is experiencing exceptional growth, reflecting the broader healthcare digitalization trend and escalating consumer demand for convenient medical services. According to IMARC Group, the global urgent care apps market size reached USD 4.6 Billion in 2025 and is projected to grow to USD 93.4 Billion by 2034, demonstrating an exceptional CAGR of 38.43% during 2026–2034. This remarkable growth rate reflects the convergence of multiple market catalysts: exponential smartphone adoption (54% of global population owns smartphones), rising healthcare costs driving demand for cost-effective alternatives, escalating chronic disease prevalence requiring immediate medical intervention, and continuous technological innovation enabling advanced AI-powered diagnostics and real-time health monitoring capabilities.
The global healthcare landscape is experiencing a transformative shift driven by technological innovation, rising smartphone penetration, and increasing demand for immediate medical assistance. At the forefront of this digital healthcare revolution is the urgent care apps market—a dynamic and rapidly expanding ecosystem of mobile applications that connect patients with immediate medical services, telemedicine consultations, and real-time healthcare guidance. From pre-hospital emergency triage systems to post-hospital medication management and rehabilitation apps, urgent care mobile applications are fundamentally reshaping how patients access and manage acute healthcare services.
Key Urgent Care Apps Market Statistics:
Base Year — 2025
Market Size in 2025 — USD 4.6 Billion
Market Forecast in 2034 — USD 93.4 Billion
Growth Rate (2026–2034) — 38.43% CAGR
Urgent Care Apps Market Drivers & Market Trends in 2026
The remarkable expansion of the urgent care apps market share is driven by multiple converging factors fundamentally reshaping healthcare delivery:
• Exponential Smartphone Penetration: Global smartphone ownership reached 54% of population (4.3 billion users) with 49% accessing mobile internet. Projected growth to 4.88 billion smartphone users by 2024 creates massive addressable market for urgent care app adoption, fundamentally enabling app-based healthcare access.
• Rising Chronic Disease Prevalence: Widespread chronic conditions requiring immediate management drive urgent care demand. For example, 129 million Americans have at least one major chronic disease, with 42% managing multiple conditions, accounting for 90% of annual healthcare expenditure of USD 4.1 trillion.
• Emergency Room Congestion and Costs: Growing demand for cost-effective alternatives to expensive emergency department visits drives urgent care app adoption, reducing unnecessary ER congestion and healthcare expenditures while improving patient convenience and accessibility.
• Traumatic Injury and Acute Condition Management: WHO data indicates 1.3 million annual deaths from road traffic accidents, with 93% occurring in low-middle income countries, creating substantial demand for accessible urgent care triaging and post-hospital rehabilitation apps.
• Advanced Technological Integration: AI-powered symptom checkers, machine learning diagnostics, IoT-enabled wearable device integration, cloud-based infrastructure, and seamless EHR connectivity enhance urgent care app functionality and user engagement, driving adoption and urgent care apps market growth.
• Government Digital Health Initiatives: Supportive government policies, regulatory frameworks promoting digital health solutions, and strategic partnerships with healthcare systems accelerate urgent care app integration into mainstream healthcare delivery models.
• 5G Network Expansion: Next-generation connectivity enables real-time video consultations, high-bandwidth health data transmission, and seamless remote patient monitoring — critical infrastructure supporting advanced urgent care app functionalities and user experience.
• Strategic Market Consolidation: Mergers and acquisitions among market players strengthen product portfolios and market reach. For example, Stryker Corporation’s acquisition of Vocera Communications and subsequent PatientSafe Solutions acquisition exemplifies consolidation driving market expansion and competitive advantage.
Request for a Sample Report for Detailed Urgent Care Apps Market Share Evaluation: https://www.imarcgroup.com/urgent-care-apps-market/requestsample
Urgent Care Apps Market Segmentation and Analysis
By App Type
• Post-Hospital Apps (44.3% market share): Dominant segment comprising medication management apps, rehabilitation support tools, and care provider communication platforms. These apps improve medication adherence, reduce costs, minimize treatment errors, and enhance patient experience through proactive care management.
• Pre-Hospital Emergency Care and Triaging Apps: Enable rapid symptom assessment, preliminary medical guidance, and emergency response coordination. Randomized clinical trials demonstrate notable reduction in medication errors, drug preparation time, and delivery time — supporting adoption and urgent care apps market growth.
• In-Hospital Communication and Collaboration Apps: Facilitate seamless clinical team coordination, real-time patient status updates, and central command center management. Examples include Pulsara HQ (web-based command center for patient coordination) and comprehensive EHR integration solutions.
By Clinical Area Type
• Trauma (37.4% market share): Leading segment addressing psychological impact from traumatic events and post-injury care management. Rising road accidents (1.3 million annual deaths) and mental health challenges drive urgent care app demand for trauma-informed care and rehabilitation support.
• Stroke Management: Immediate symptom recognition and emergency response coordination critical for optimal patient outcomes. Real-time communication between patients and stroke specialists enabled by urgent care apps supports comprehensive emergency care.
• Cardiac Conditions: Acute cardiac events require immediate medical intervention and expert guidance. Urgent care apps facilitate rapid assessment, remote consultation with cardiologists, and continuous monitoring — supporting comprehensive cardiac emergency care management.
Global Regional Market Analysis and Growth Outlook
The urgent care apps market analysis reveals significant regional variations driven by healthcare infrastructure, smartphone adoption rates, government digital health policies, and healthcare digitalization progress.
• North America (38.2% market share): Market leader driven by advanced healthcare infrastructure, high smartphone penetration, robust telemedicine adoption, supportive government digital health initiatives, and strong venture capital investment in healthcare technology. Strategic partnerships and acquisitions strengthen competitive positioning.
• United States (89.70% North America share): Leading market driven by healthcare digitalization, AI-powered diagnostics, wearable device integration, and FDA-regulated medical apps. U.S. digital health startups raised USD 10.1 Billion in 2024, driving urgent care apps market innovation and adoption.
• Europe: Expanding market supported by broader telehealth growth (USD 5.7 Billion in 2024, projected USD 23.4 Billion by 2033 at 17.1% CAGR). AI-enhanced diagnostics, favorable regulations, and digital health transformation drive urgent care app integration into mainstream healthcare systems.
• Asia-Pacific: Rapidly expanding market driven by smartphone adoption (Indian market grew 7.2% to 69 million units in H1 2024), digital health initiatives, telemedicine integration, and population healthcare needs. Growing smartphone connectivity accelerates urgent care app penetration across the region.
• Latin America: Expanding market supported by internet penetration (nearly 80% in urban areas), mobile healthcare solution adoption, telemedicine expansion, and digital healthcare transformation initiatives enhancing medical accessibility and urgent care app adoption.
• Middle East and Africa: Emerging opportunities driven by telehealth growth (Saudi Arabia telehealth market reached USD 657.2 Million in 2024, projected 20.6% CAGR to reach USD 4,112.7 Million by 2033). Mobile health technologies and digital healthcare initiatives drive urgent care apps market expansion.
Competitive Landscape and Leading Market Players
The global urgent care apps market features companies pursuing aggressive strategies to capture market share through technological innovation, strategic partnerships, and enhanced user experience. Key market players include:
• Alayacare
• Allm Inc.
• CommuniCare Technology Inc.
• Imprivata Inc.
• Medisafe
• Siilo
• TigerConnect Inc.
• Twiage Solutions Inc.
• Vocera Communications Inc. (Stryker Corporation)
These market leaders are investing in AI-driven diagnostics, biometric patient identification, cloud-based platforms, EHR interoperability, HIPAA-compliant infrastructure, and strategic acquisitions to strengthen urgent care apps market positioning and drive innovation in real-time healthcare delivery.
About Us:
IMARC Group is a leading global market research company providing comprehensive data-driven insights and strategic consulting services to healthcare organizations, technology companies, investors, and stakeholders seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, researchers, and analysts, IMARC delivers thorough, reliable market intelligence across healthcare technology, digital health, medical devices, telemedicine, pharmaceuticals, and numerous other sectors. The firm’s specialized research capabilities enable healthcare providers, technology developers, venture capital investors, and other market participants to make informed decisions regarding market opportunities, competitive positioning, product development strategies, and investment decisions within the dynamic and rapidly expanding urgent care apps market ecosystem.
Contact Us:
IMARC Group
United States: +1–201–971–6302
India: +91–120–433–0800
United Kingdom: +44–753–714–6104
Email: sales@imarcgroup.com
 English
Join our community to interact with posts!