
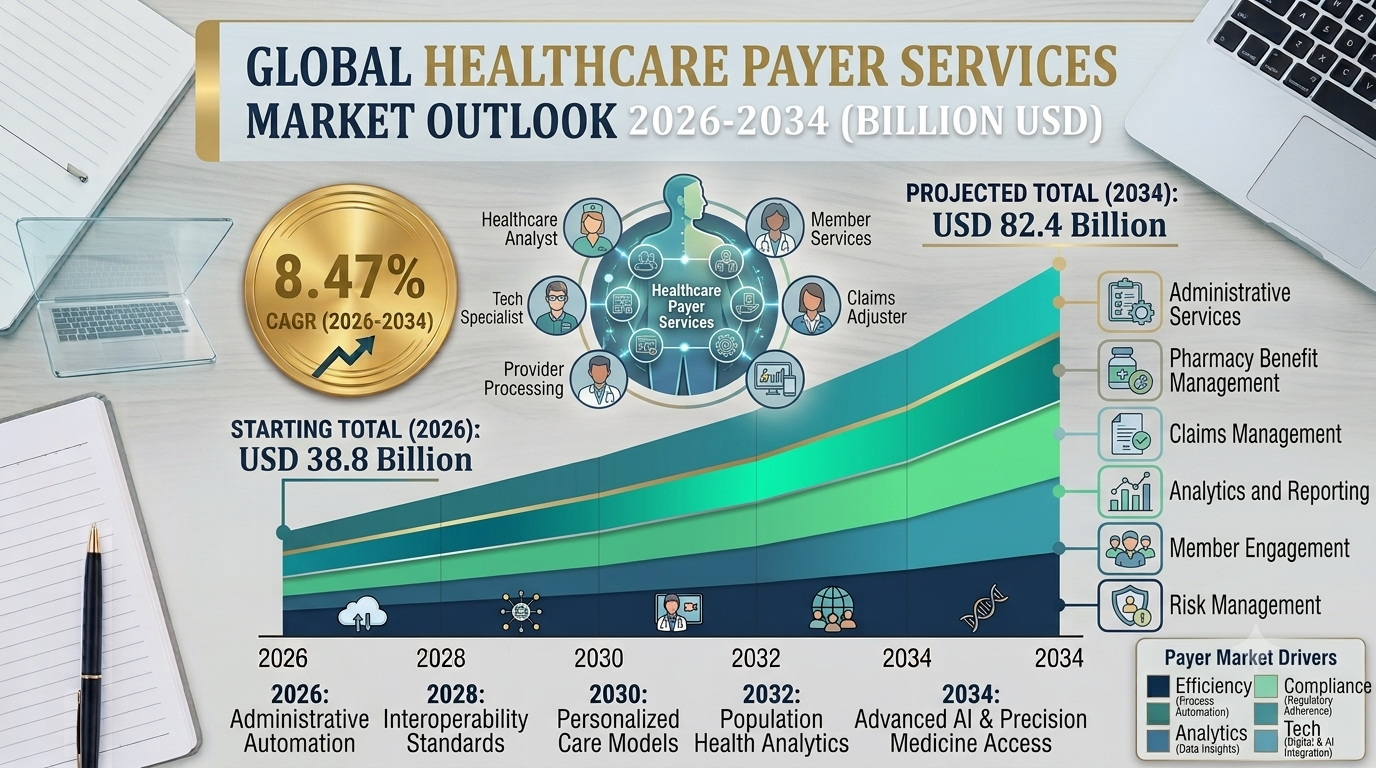
According to IMARC Group, the global healthcare payer services market size reached USD 38.8 Billion in 2025 and is projected to reach USD 82.4 Billion by 2034, expanding at a CAGR of 8.47% during 2026-2034. North America currently leads the healthcare payer services market share, holding over 74.9% of the market in 2025. This robust growth reflects changing healthcare regulations, an aging global population, the rising importance of healthcare data security, and growing patient demand for personalized, accessible healthcare experiences.
Healthcare Payer Services Industry Overview
Healthcare payer services encompass the outsourced business, information technology, and knowledge process functions that insurers and health plans rely on to run day-to-day operations efficiently. Rather than building every capability in-house, payers partner with specialized service providers to manage high-volume, process-intensive functions while retaining focus on core underwriting, member care, and strategic decision-making.
Healthcare payer services are deployed across a broad continuum of use cases:
- Claims management: End-to-end claims adjudication, data entry, verification, and processing to accelerate reimbursement and reduce errors
- Member management: Enrollment, member services, and support functions that shape policyholder satisfaction and retention
- Provider management: Provider network administration and payer-provider communication and credentialing support
- Analytics and fraud management: Data-driven identification of fraud, waste, and abuse, alongside population health and predictive analytics
- Billing, accounts, and HR services: Back-office financial and workforce administration supporting payer operations at scale
Request for a Sample Report for Detailed Healthcare Payer Services Market Share Evaluation: https://www.imarcgroup.com/healthcare-payer-services-market/requestsample
Global Healthcare Payer Services Market Size & Key Statistics
Below are the key healthcare payer services market size statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Healthcare Payer Services Market Size in 2025 | USD 38.8 Billion |
| Market Forecast in 2034 | USD 82.4 Billion |
| Market Growth Rate (2026-2034) | 8.47% CAGR |
| Largest Region | North America (74.9% share) |
| Leading Type Segment | BPO Services |
| Leading Application Segment | Claims Management Services (33.8% share) |
| Leading End-Use Segment | Private Payers (59.0% share) |
Key Market Drivers & Healthcare Payer Services Market Trends in 2026
Several powerful forces are shaping Healthcare Payer Services Market Trends and fuelling sustained growth expectations across the global payer outsourcing landscape:
1. Rising Demand for Cost-Effective, Scalable Payer Operations
Escalating healthcare costs are propelling payers to outsource non-core activities such as claims processing, member services, and analytics to specialized providers. This reduces administrative burden, improves service quality, and gives payers the flexibility to scale outsourcing requirements up or down as claim volumes and regulations evolve.
2. Accelerating Adoption of AI, Automation, and Analytics
The adoption of artificial intelligence, machine learning, robotic process automation, and data analytics is transforming payer operations, enabling more accurate decision-making and streamlined claims adjudication. In the United States, AI-driven claims adjudication technologies increased processing speed and accuracy by 30%-50% in 2023 while cutting errors by a similar margin, underscoring the operational upside specialized payer service providers unlock.
3. Expanding Digital Health Transformation
The World Bank's commitment to raise digital health spending from 6% to 8% by 2030 highlights the accelerating shift toward digital-first payer operations. Digital claims adjudication, enrollment platforms, telehealth support, and interoperability initiatives are pushing payers to rely on specialized providers with the infrastructure to navigate this transition.
4. Rising Adoption of Analytics for Fraud Detection and Population Health
The global big data market in healthcare was valued at USD 67 Billion in 2023 and is projected to grow at a CAGR exceeding 19% through 2035. Payer service providers apply advanced analytics across claims, clinical records, and patient histories to detect fraud, forecast disease outbreaks, and enable proactive population health management.
5. Growing Base of Insured Individuals Worldwide
The healthcare insurance sector is expected to strengthen further as chronic illnesses are projected to rise by 99.5% by 2050. In the UK alone, the number of privately insured individuals rose 83% between 2021 and 2022, reaching 11.7 million. This expanding insured base is driving claim volumes, policy management workloads, and member service demand across payer organizations.
6. Shift Toward Value-Based Care Models
As reimbursement increasingly ties to patient outcomes, payers are investing in analytics and care management services delivered through specialized partners, reinforcing sustained market growth across both private and public payer segments.
7. Stringent Regulatory and Data Security Requirements
Evolving mandates such as the Health Insurance Portability and Accountability Act (HIPAA) in the United States and GDPR in Europe are compelling payers to lean on specialized service providers with deep regulatory and cybersecurity expertise to remain compliant while managing growing volumes of sensitive healthcare data.
Key Market Segmentation
By Type
BPO Services -- Largest Segment: Business process outsourcing leads the type segment in 2025, encompassing claims processing, enrollment, billing, and member services. BPO providers deliver significant cost savings alongside the scalability payers need to adjust outsourcing requirements as regulations and market dynamics shift, while streamlining processes and reducing errors through dedicated technology infrastructure.
ITO Services: Information technology outsourcing supports payers' digital claims adjudication platforms, data security infrastructure, and system interoperability initiatives.
KPO Services: Knowledge process outsourcing delivers higher-value analytical and research-driven support, including advanced fraud analytics and clinical data interpretation.
By Application
Claims Management Services -- Largest Segment (33.8% share): Claims management leads application demand as payers offload data entry, verification, and processing to specialized providers, resulting in faster claims resolution, reduced errors, and improved customer satisfaction through advanced automation and data analytics.
Analytics and Fraud Management Services: Providers apply predictive analytics and pattern detection to identify fraud, waste, and abuse across large claims and clinical datasets.
Integrated Front Office Service and Back Office Operations: Combines member-facing support with administrative back-office processing for end-to-end operational continuity.
Member Management Services: Covers enrollment, policy administration, and member support functions central to policyholder retention.
Provider Management Services: Supports provider network administration, credentialing, and payer-provider communication.
Billing and Accounts Management Services: Manages payer-side financial operations, invoicing, and accounts reconciliation.
HR Services: Delivers workforce administration support for large payer organizations.
By End Use
Private Payers -- Largest Segment (59.0% share): Insurance companies and employer-sponsored health plans dominate end-use demand, relying on healthcare payer services to streamline claims, enrollment, and customer service while achieving cost containment, scalability, and regulatory compliance amid fluctuating membership volumes.
Public Payers: Government-backed programs increasingly outsource administrative and operational functions to expand healthcare access, improve affordability, and manage growing enrollment under national health initiatives.
Regional Healthcare Payer Services Market Analysis
| Region | Key Highlights |
| North America -- Largest (74.9% share) | United States & Canada; complex public-private payer network, high claims volumes, strong HIPAA-driven demand for data security and compliance expertise, home to leading global payer service providers |
| Europe | Germany, France, UK, Italy, Spain, Russia; eHealth and European Health Data Space initiatives, GDPR compliance needs, rising demand for analytics and fraud management amid an aging population |
| Asia Pacific | China, Japan, India, South Korea, Australia, Indonesia; expanding health insurance coverage under programs like India's Ayushman Bharat, rapid digitization of healthcare systems, rising healthcare expenditure |
| Latin America | Brazil, Mexico; growth in private insurance uptake alongside public coverage systems such as Brazil's SUS, rising demand for low-cost administrative outsourcing solutions |
| Middle East & Africa | GCC nations including Saudi Arabia and UAE; mandatory health insurance programs, healthcare modernization initiatives, growing adoption of member services and claims management outsourcing |
North America dominates the global Healthcare Payer Services Market Share, accounting for over 74.9% in 2025, underpinned by the United States' complex mix of private and public insurance programs, stringent HIPAA compliance requirements, and rapid adoption of digital health solutions, electronic health records, and telemedicine.
Asia Pacific represents one of the fastest-growing regional markets, driven by expanding insurance coverage under national health missions such as India's Ayushman Bharat, rising healthcare expenditure in China, and increasing adoption of telemedicine and mobile health solutions across the region.
Connect for Detailed Healthcare Payer Services Market Share Segmentation Analysis -- Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=3879&flag=C
Leading Players in the Global Healthcare Payer Services Industry
The global healthcare payer services market features a mix of diversified IT and business process outsourcing giants alongside specialized healthcare consulting firms. Key companies covered in the IMARC Group report include:
- Accenture plc
- Cognizant Technology Solutions Corporation
- Concentrix Corporation
- ExlService Holdings Inc.
- Genpact Limited
- HCL Technologies Limited
- Hinduja Global Solutions Limited
- HP Development Company L.P.
- McKesson Corporation
- UnitedHealth Group Incorporated
- Wipro Limited
- Xerox Corporation
Latest Healthcare Payer Services Market Industry Developments
October 2024 -- Accenture plc
Accenture acquired healthcare consulting company Consus Health, integrating its value-based care and payer-provider collaboration capabilities to strengthen Accenture's healthcare payer services portfolio and expand its healthcare consulting business.
September 2024 -- CorroHealth
CorroHealth acquired the healthcare revenue cycle management (RCM) division of Navient, strengthening its capacity to deliver complete RCM solutions including coding, auditing, and financial management services to healthcare providers.
August 2023 -- Accenture plc
Accenture acquired ATI Solutions Group, a Perth-based consulting provider, to help clients in Australia automate field operations more efficiently.
August 2023 -- Cognizant
Cognizant announced plans to leverage Google Cloud's generative AI technology to develop new healthcare large language model (LLM) solutions addressing healthcare-related business challenges.
March 2023 -- Concentrix Corporation
Concentrix announced a strategic agreement to merge with Webhelp in a transaction valued at approximately USD 4.8 Billion, including net debt, expanding its global customer experience and payer services capabilities.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
 English
Join our community to interact with posts!