
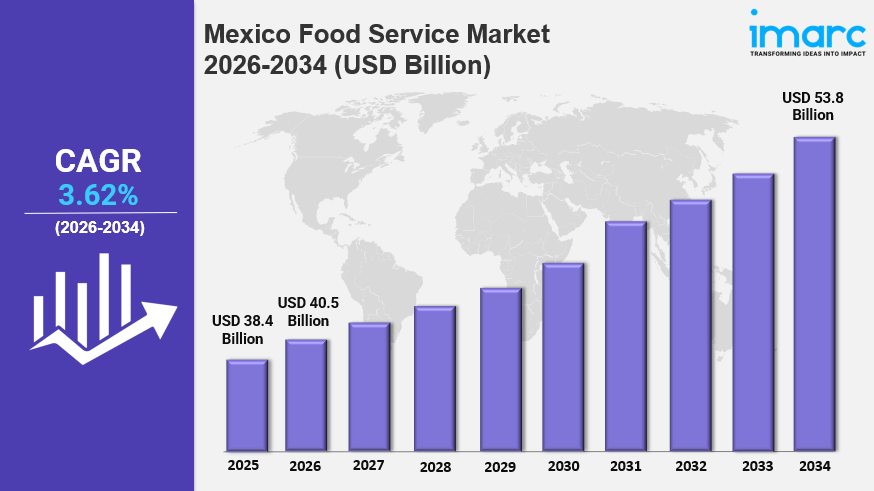
IMARC Group has recently released a report titled “Mexico Food Service Market Size, Share, Trends and Forecast by Sector, System, Type of Restaurant, and Region, 2026-2034”, providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.
Mexico Food Service Market Size and Forecast 2026–2034
The Mexico food service market size increased from USD 38.4 Billion in 2025 to USD 40.5 Billion in 2026 and is projected to reach USD 53.8 Billion by 2034, exhibiting a CAGR of 3.62% during 2026–2034. The market outlook is driven by rapid urbanization, changing consumer lifestyles, and rising demand for convenient dining options. Expanding tourism, growing adoption of online ordering platforms, and a rising middle class are further supporting the sector's growth, with operators increasingly investing in improving customer experience and operational efficiency.
In 2026, Mexico food service market growth is being fueled by operators' continued push toward digital-first customer experiences, as consumers increasingly favor speed and convenience over traditional dine-in formats. Established players such as FEMSA are launching app-enabled, drive-thru-style concepts aimed at fast, personalized service for on-the-go shoppers. Restaurant chains and delivery platforms are broadening their digital footprint and refining operations to capture Mexico's increasingly tech-savvy and convenience-driven consumer base.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020–2025
- Forecast Period: 2026–2034
- Market Size (2025): USD 38.4 Billion
- Market Size (2026): USD 40.5 Billion
- Projected Size (2034): USD 53.8 Billion
- Growth Rate: CAGR of 3.62%
Explore Opportunities in the Mexico Food Service Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-food-service-market/requestsample
Mexico Food Service Market Growth: Key Trends and Market Insights
Mexico food service market growth is supported by a rapid shift toward digital ordering and delivery, as consumers increasingly rely on smartphones and internet access to order from their preferred restaurants and food suppliers. Third-party delivery platforms and branded digital ordering channels continue to expand, streamlining the customer journey and encouraging repeat purchases. This mirrors Mexico's broader digital transformation, with online food ordering seeing a marked rise in adoption, supporting a favorable long-term outlook for the sector through 2034.
Key Mexico food service market trends also include a growing emphasis on healthier menu offerings, as rising health and wellness awareness prompts operators to introduce low-calorie, plant-based, and organic options. Platforms such as Rappi, which serves a large and growing user base across Latin America, have expanded rapid-delivery services covering both food and pharmacy items. Restaurants and food service chains are increasingly adding low-sodium, gluten-free, and vegan choices to their menus, reflecting a broader societal shift toward mindful eating that is expected to sustain market growth.
Sustainability is emerging as another important focus area, with food service operators adopting practices that reduce food and packaging waste and prioritize responsibly sourced ingredients. Many restaurants, caterers, and fast-food chains are incorporating local and seasonal produce, sustainably sourced seafood and meats, and eco-friendly packaging into their operations. This growing commitment to sustainable practices aligns with international environmental goals and is increasingly valued by environmentally conscious consumers, reinforcing the Mexico food service market outlook through 2034.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33119&flag=C
Mexico Food Service Market Segmentation Analysis
The Mexico food service market is segmented by sector, system, type of restaurant, and region, offering a comprehensive view of consumer preferences, operational models, and regional dynamics across the country.
Breakup by Sector
- Commercial: Encompasses restaurants, cafes, and other outlets operating primarily for profit, serving the majority of everyday consumer dining and takeaway demand.
- Non-commercial: Covers institutional food service such as workplace cafeterias, educational institutions, and healthcare facilities operating outside a primary profit motive.
Breakup by System
- Conventional Foodservice System: Involves on-site preparation and service, remaining common across full-service restaurants and traditional dining establishments.
- Centralized Foodservice System: Relies on a central kitchen to prepare food for distribution across multiple outlets, supporting consistency and scale.
- Ready Prepared Foodservice System: Uses pre-cooked and chilled or frozen meals that are reheated on-site, valued for efficiency and reduced labor needs.
- Assembly-Serve Foodservice System: Relies on pre-prepared components assembled and served quickly, well suited to fast-casual and quick-service formats.
Breakup by Type of Restaurant
- Fast Food Restaurants: Continue to see strong demand driven by affordability, speed, and wide accessibility across urban and suburban areas.
- Full-Service Restaurants: Cater to consumers seeking a complete dine-in experience, supported by growing tourism and rising discretionary spending.
- Limited Service Restaurants: Appeal to convenience-focused consumers through streamlined ordering and reduced table service.
- Special Food Services Restaurants: Include catering and event-based food services, benefiting from growth in corporate and social gatherings.
Breakup by Region
- Northern Mexico: Benefits from proximity to the United States, higher income levels, and strong demand for international restaurant chains and delivery services.
- Central Mexico: Anchored by Mexico City's large urban population, tourism inflows, and dense concentration of dining establishments.
- Southern Mexico: An emerging market as tourism, urbanization, and digital ordering adoption gradually expand access to food service options.
- Others: Include remaining regions where evolving retail and delivery infrastructure continue to broaden food service reach.
Competitive Landscape
The Mexico food service market features a mix of established multinational restaurant chains, regional operators, and emerging digital-first delivery platforms. The report provides a comprehensive analysis of the competitive landscape, covering market structure, key player positioning, top winning strategies, a competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies.
Market participants are competing through digital ordering innovation, menu diversification, and expanded delivery partnerships. Leading platforms are broadening their service offerings to include new categories such as retail and pharmacy delivery, while major restaurant chains are investing in app-based ordering and loyalty programs. Companies with strong digital infrastructure and delivery networks are best positioned to capture Mexico's increasingly convenience-driven consumer base.
Latest News and Developments
- May 2024: Uber Eats partnered with Costco in Mexico, enabling customers to order Costco products for delivery without requiring a membership, strengthening its competitive position within Mexico's fast-growing food service and delivery sector.
- December 2023: Alsea announced plans to invest MX$550 million in 2024 to expand its Domino's Pizza operations in Mexico, with a focus on scaling digital ordering channels toward a larger share of overall sales.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
 English
Join our community to interact with posts!