
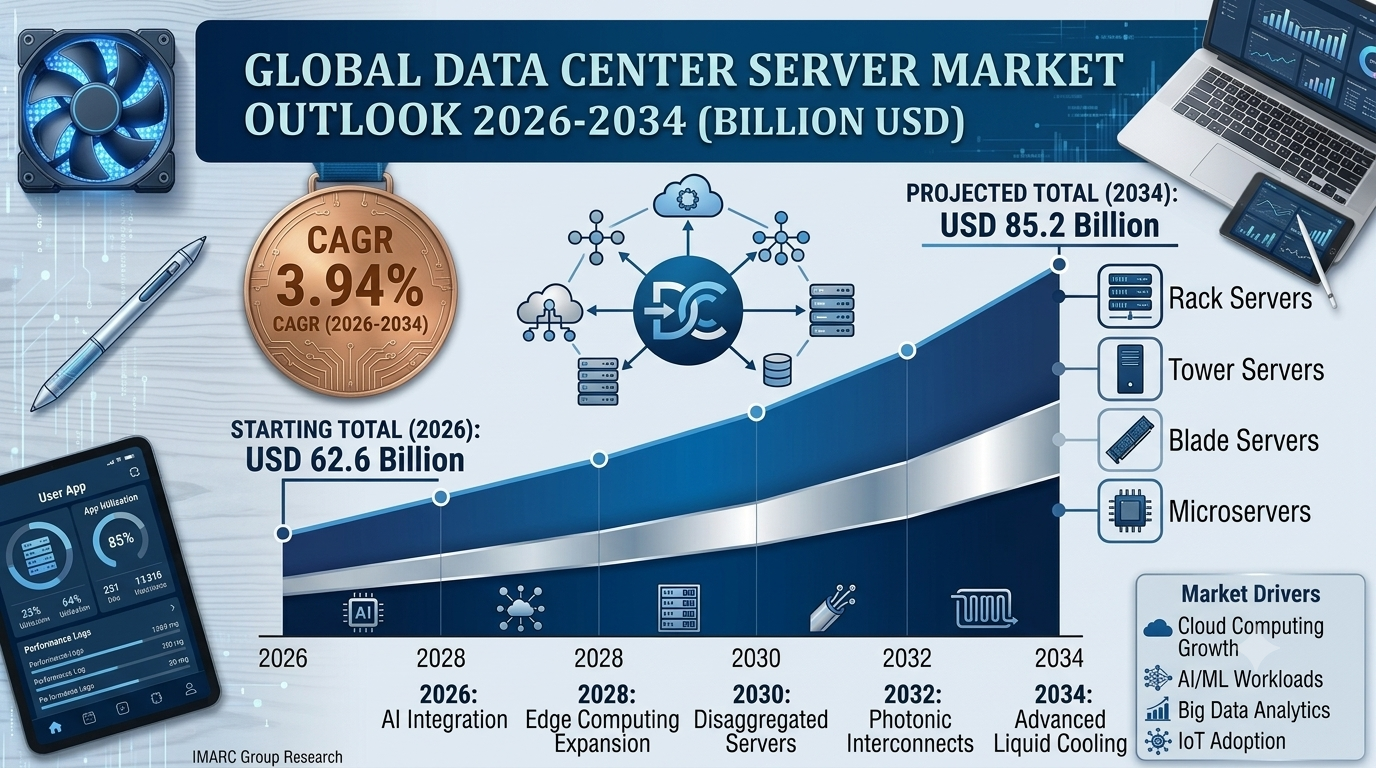
According to IMARC Group, the global data center server market size reached USD 59.6 Billion in 2025, increased to USD 62.6 Billion in 2026, and is projected to reach USD 85.2 Billion by 2034, expanding at a CAGR of 3.94% during 2026–2034. This steady data center server market growth reflects accelerating AI and machine learning workload deployments by hyperscalers and enterprises, rapid cloud-native application proliferation, and escalating global digital transformation programs.
Data Center Server Industry Overview
A data center server is a high-performance computing system designed and optimized for continuous operation within controlled data center environments, providing compute, storage, and network processing capabilities for enterprise applications, cloud services, AI workloads, and digital infrastructure. Server configurations are defined by form factor, processor architecture, memory capacity, storage density, GPU acceleration capability, and thermal management approach.
Data center servers support a broad continuum of deployment environments:
- Hyperscale cloud computing: Compute infrastructure for AWS, Microsoft Azure, Google Cloud, and other hyperscale operators
- AI training and inference: GPU-dense rack and blade servers powering large language model training and generative AI deployment
- Enterprise IT modernization: On-premises and hybrid cloud infrastructure supporting financial services, healthcare, and manufacturing workloads
- Edge and distributed computing: Micro and compact servers enabling low-latency AI inference, 5G-connected IoT, and industrial automation
- Industrial and operational technology: Rugged, temperature-tolerant servers for manufacturing automation, energy grid management, and smart city applications
Global Data Center Server Market Size & Key Statistics
Below are the key data center server market size statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Data Center Server Market Size in 2025 | USD 59.6 Billion |
| Data Center Server Market Size in 2026 | USD 62.6 Billion |
| Market Forecast in 2034 | USD 85.2 Billion |
| Market Growth Rate (2026–2034) | 3.94% CAGR |
| Largest Region | North America (38.7% share, 2025) |
| Leading Product Segment | Rack Servers (46.5%, 2025) |
| Fastest-Growing Product Segment | Micro Servers (~5.1% CAGR) |
| Leading Application Segment | Commercial Servers (64.3%, 2025) |
Request for a Sample Report for Detailed Data Center Server Market Share Evaluation: https://www.imarcgroup.com/data-center-server-market/requestsample
Key Market Drivers & Data Center Server Market Trends in 2026
Several powerful forces are shaping data center server market trends and fuelling sustained growth expectations across global digital infrastructure markets:
1. AI and Machine Learning Workload Explosion
Worldwide data center capital expenditures increased 57% in 2025, with the top four US cloud service providers expanding capex by 76%, driven almost entirely by AI infrastructure investment that requires GPU-dense rack and blade server deployments at unprecedented scale. Revenue from servers with embedded GPUs grew 49.4% year-over-year in Q3 2025 and accounted for over half of total server market revenue.
2. Hyperscale Cloud Expansion Supercycle
Nearly 100 GW of new data center capacity is projected to be added globally between 2026 and 2030, effectively doubling total capacity, with each gigawatt of new capacity requiring thousands of server units across all product categories — a defining force behind Data Center Server Market Growth through 2034.
3. Enterprise Digital Transformation Investment
Worldwide datacenter systems spending rose 46.8% to USD 489.5 Billion in 2025, reflecting broad enterprise adoption of hybrid cloud, real-time analytics, and AI-powered automation that requires sustained server refresh cycles across financial services, healthcare, manufacturing, and public sector verticals.
4. AI-Optimized Server Architectures Displacing General-Purpose Compute
The transition from general-purpose CPU-centric configurations to AI-optimized platforms featuring NVIDIA Blackwell, AMD Instinct MI300X, and Intel Gaudi3 accelerators is reshaping the entire server OEM competitive landscape, with AI-driven demand now the primary growth engine in the industry.
5. Edge Computing Proliferation
Global active data center IT capacity is set to grow sixfold from 24 GW in 2025 to 147 GW by 2035, with a growing share destined for distributed edge deployments requiring micro and compact server configurations across telecommunications, retail, and industrial environments.
6. Liquid Cooling Integration Driving Next-Generation Server Design
Modern AI racks drawing 100 kW or more per rack — versus 5–15 kW for general-purpose CPU racks — are making direct liquid cooling, rear-door heat exchangers, and full immersion cooling standard design requirements rather than premium options.
7. Component Supply Chain Constraints
The AI boom has created unprecedented DRAM and high-bandwidth memory shortages, with Dell, Lenovo, HPE, and other OEMs announcing server price increases of 10–20% in late 2025 and early 2026 driven by memory cost escalation.
Key Market Segmentation
By Product
Rack Servers – Largest Segment: Rack servers command a dominant 46.5% share of the market in 2025, reflecting their unmatched compute density, GPU compatibility, and universal applicability across hyperscale cloud and enterprise architectures. Their standardized 1U–4U form factors maximize space utilization, making them the preferred platform for AI training and inference workloads.
Blade Servers: At 24.8% share, blade servers offer superior resource sharing through centralized chassis-level power and cooling, preferred in enterprise environments consolidating virtualization workloads.
Micro Servers: The fastest-growing product segment at ~5.1% CAGR, driven by edge computing proliferation, distributed AI inference, and 5G-connected IoT infrastructure requiring compact, power-efficient compute.
Tower Servers: Serve small and mid-sized enterprise deployments and remote office environments requiring standalone, low-complexity compute infrastructure.
By Application
Commercial Servers – Largest Segment: Commercial servers account for 64.3% of the market in 2025, underscoring the dominant role of hyperscale cloud operators, financial services, e-commerce platforms, and SaaS providers. Explosive growth of AI-as-a-Service and generative AI platforms sustains continuous server procurement.
Industrial Servers: At 35.7% share, industrial servers serve manufacturing automation, process control, energy grid management, transportation, and smart city applications, specifying rugged, temperature-tolerant, and extended-lifecycle platforms driven by Industry 4.0 adoption.
Regional Data Center Server Market Analysis
| Region | Key Highlights |
| North America – Largest (38.7%) | US & Canada; hyperscaler capex supercycle, AI infrastructure build-out, CHIPS Act fab investment, enterprise IT modernization |
| Europe (24.5%) | Germany, France, UK, Italy; sovereign cloud mandates, EU AI Act compliance infrastructure, Industry 4.0 digitalization, green data center investment |
| Asia Pacific (22.8%) | China, Japan, India, South Korea; hyperscale buildout, India's digital infrastructure program, semiconductor reinvestment, ASEAN cloud adoption |
| Middle East & Africa (7.1%) – Fastest Growing | GCC Vision 2030 smart infrastructure, NEOM digital platform, sovereign AI cloud strategies, African digital economy |
| Latin America (6.9%) | Brazil AI data center platform, Mexico nearshoring enterprise IT, Chile colocation hub development, regional cloud growth |
North America leads the global Data Center Server Market Share, underpinned by the unparalleled concentration of hyperscale cloud operators including AWS, Microsoft, Google, and Meta, combined with the highest enterprise IT modernization investment and sustained AI infrastructure build-out of any global region. Over 35 GW of data center capacity is currently under construction in North America, 60% of which is already pre-leased.
The Middle East and Africa region is the fastest-growing market at ~4.5% CAGR, driven by GCC Vision 2030 smart infrastructure investment and sovereign AI cloud development, while India represents the most significant emerging market through 2034, supported by a USD 15 billion digital infrastructure investment program for 2026–2030.
Connect for Detailed Data Center Server Market Share Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=1131&flag=C
Leading Players in the Global Data Center Server Industry
The global data center server market is moderately concentrated, with established technology OEMs competing aggressively across rack, blade, micro, and tower server segments. Key companies covered in the IMARC Group report include:
| Company | Key Products | Competitive Strength |
| Hewlett Packard Enterprise | ProLiant Gen11, Gen12, ProLiant XD685 | AI Factory strategy, GreenLake hybrid cloud, liquid-cooled Blackwell platforms |
| Dell, Inc. | PowerEdge Servers | AI-optimized server leader, NVIDIA Blackwell shipments, enterprise services ecosystem |
| Cisco Systems, Inc. | UCS C-Series, X-Series | Converged server-network platform, secure AI factory architecture |
| Lenovo | ThinkSystem SR, ThinkAgile HX, Neptune liquid-cooled | Fastest-growing top-5 vendor, Asia-Pacific strength, Neptune DLC leadership |
| Super Micro Computer, Inc. | X14 Series, X13 Series, DCBBS | GPU server specialist, hyperscale direct relationships, fast time-to-market |
| Huawei Technologies Co., Ltd. | FusionServer Pro, TaiShan 200 series | China domestic leader, ARM-based ecosystem, domestic GPU alternatives |
| Fujitsu Ltd. | PRIMERGY M7, PRIMEQUEST, PRIMEHPC FX | Japan and EU markets, HPC strength, Fugaku successor platforms |
Latest Data Center Server Market Industry Developments
December 2025 – Hewlett Packard Enterprise
HPE expanded its collaboration with NVIDIA to accelerate AI adoption across government and enterprise sectors by introducing secure AI factory solutions, providing integrated, scalable infrastructure that simplifies AI deployment while ensuring data security and compliance.
Late 2025 – Dell, Inc.
Dell announced server price increases of 10–20% driven by DRAM and HBM cost escalation, while simultaneously expanding its AI Factory with NVIDIA as a complete enterprise AI platform integrating compute, networking, and storage.
February 2026 – Lenovo
Lenovo reorganized its Infrastructure Solutions Group to improve profitability amid strong AI-driven demand, reporting record quarterly revenue with double-digit gains across devices, infrastructure, and services.
March 2026 – Super Micro Computer, Inc.
Supermicro launched seven AI data platform solutions in partnership with NVIDIA and ecosystem partners, reinforcing its GPU-dense rack server positioning for hyperscale AI training and expanding its edge inference product range.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104
 English
Join our community to interact with posts!