
IMARC Group has recently released a new research study titled "Mexico Offshore Wind Power Market Size, Share, Trends and Forecast by Installation, Water Depth, Capacity, and Region, 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
Mexico Offshore Wind Power Market Size & Share 2026-2034
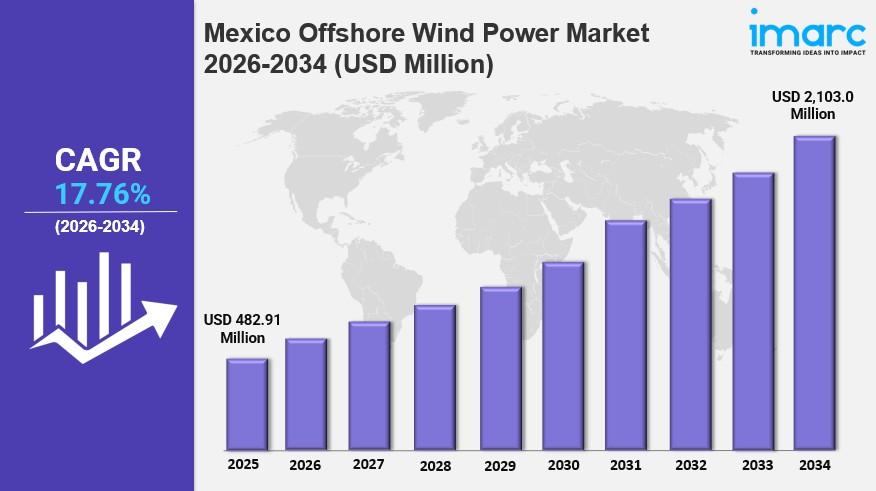
The Mexico offshore wind power market size was valued at USD 482.91 Million in 2025 and is projected to reach USD 2,103.0 Million by 2034, expanding at a CAGR of 17.76% during 2026-2034. Mexico's offshore wind power sector is gaining significant momentum driven by the country's commitment to generating clean energy and reducing greenhouse gas emissions, with the government's ambitious renewable energy targets accelerating interest in offshore wind development.
Abundant wind resources along extensive coastlines spanning both the Gulf of Mexico and Pacific Ocean, combined with technology cost reductions and growing private sector investment, continue to support market expansion in 2026. Mexico holds an estimated 487.3 gigawatts of installable offshore wind capacity in viable development areas across the Gulf of Mexico, Gulf of Tehuantepec, and Baja California, signifying five times more capacity than the country's total power generation installed in 2023, strengthening the Mexico offshore wind power market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 482.91 Million
- Projected Market Size (2034): USD 2,103.0 Million
- Growth Rate: CAGR of 17.76% (2026-2034)
Explore Opportunities in the Mexico Offshore Wind Power Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-offshore-wind-power-market/requestsample
Key Growth Drivers and Trends in the Mexico Offshore Wind Power Market
Growth in the Mexico offshore wind power market is being driven by national renewable energy targets and policy mandates, as government commitments establishing mandatory clean energy generation targets under national law and international climate agreements push utilities and private developers to explore large-scale renewable options beyond onshore wind and solar. The Energy Transition Law requires the country to generate 35% of electricity from clean sources by 2024, motivating grid operators to plan future infrastructure capable of handling offshore power integration and accelerating feasibility studies along suitable coastlines.
One of the leading Mexico offshore wind power market trends is enhanced focus on grid infrastructure development, as research conducted by the National Renewable Energy Laboratory (NREL) in 2024 identified coordinated transmission planning as essential for effectively connecting offshore wind resources to onshore end users. The existing oil and gas industry infrastructure positioned in the Gulf of Mexico offers potential for shared transmission systems and workforce utilization, supporting more efficient project development.
Another key factor supporting Mexico offshore wind power market growth is accelerating adoption of high-capacity turbine technology, as developers prioritize energy efficiency and cost optimization. In March 2024, Sempra Infrastructure announced a positive final investment decision for the Cimarron wind project, a 320 Megawatt facility representing the third phase of the Energía Sierra Juarez (ESJ) wind complex in Baja California, backed by a twenty-year power purchase agreement and an investment of around USD 550 Million, reflecting the growing scale of private sector commitment to Mexico's renewable energy infrastructure.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=34193&flag=C
Mexico Offshore Wind Power Industry Segmentation Insights
Breakup by Installation:
- Fixed Structure: Dominates the market with an 85% share in 2025, owing to proven technology reliability in shallow water deployments, lower capital expenditure requirements compared to floating alternatives, and the prevalence of suitable shallow-water sites along Mexico's continental shelf.
- Floating Structure: Represents an emerging segment as advancements in turbine technology improve feasibility in deeper waters, strengthening long-term project viability beyond shallow coastal zones.
Breakup by Water Depth:
- Up to 30m: Leads with a 62% share in 2025, owing to significantly reduced installation complexity using monopile foundations, established supply chain infrastructure, and favorable seabed conditions along key coastal development zones.
- Above 30m: Represents a growing segment as technological advancements enable developers to expand into deeper water sites with strong wind resource potential.
Breakup by Capacity:
- Up to 3MW: Serves smaller-scale offshore wind installations suited to specific site and grid conditions.
- 3MW to 5MW: Represents a mid-range capacity segment balancing installation cost and energy output.
- Above 5MW: Represents the largest segment with a 70% share in 2025, attributable to superior energy capture efficiency, lower levelized cost of energy per megawatt-hour generated, and growing manufacturer focus on larger turbine platforms for commercial-scale projects.
Breakup by Region:
- Northern Mexico: An emerging region for offshore wind development due to strong coastal wind resources, proximity to industrial hubs, and growing electricity demand from manufacturing and export-oriented industries.
- Central Mexico: Benefits from rising urban power usage and industrial activity encouraging investment in renewable power sources, along with proximity to financial institutions and policymakers.
- Southern Mexico: Offers strong offshore wind potential due to favorable coastal geography and consistent wind patterns, supported by growing energy needs from industrial activity and tourism-driven development.
- Others: Comprises additional coastal regions contributing to Mexico's broader offshore wind development pipeline.
Key Challenges and Growth Opportunities in the Mexico Offshore Wind Power Market
The Mexico offshore wind power market faces challenges including electrical grid infrastructure limitations that restrict the ability to transmit electricity from coastal generation sites to inland consumption centers, along with regulatory framework uncertainty and complex permitting requirements across multiple government agencies. High initial capital investment requirements for foundation construction, turbine procurement, and specialized installation vessels also present financing challenges, particularly for early-stage projects lacking operational track records in Mexican waters.
Despite these challenges, the market offers considerable growth opportunities driven by Mexico's abundant maritime wind resources across the Gulf of Mexico and Pacific Ocean, growing electricity demand tied to rapid urbanization, and declining offshore wind technology costs improving project economics. Growing private sector interest, international collaboration, and improving project financing mechanisms are expected to accelerate the transition from planning phases to active construction, creating substantial opportunities for long-term growth in the Mexico offshore wind power market.
Competitive Landscape
The Mexico offshore wind power market competitive landscape is characterized by emerging positioning among international energy developers, turbine manufacturers, and infrastructure companies anticipating market growth. The sector exhibits early-stage dynamics with limited operational capacity but growing developer interest as regulatory frameworks mature and feasibility assessments demonstrate project viability. International offshore wind specialists bring global deployment experience while domestic energy companies contribute local market knowledge and grid integration expertise, with strategic partnerships between foreign developers and Mexican partners anticipated to intensify as project opportunities advance toward procurement stages.
Recent Developments in the Mexico Offshore Wind Power Market
- March 2024: Sempra Infrastructure announced a positive final investment decision for the Cimarron wind project, a 320 Megawatt facility representing the third phase of the Energía Sierra Juarez wind complex in Baja California, backed by a twenty-year power purchase agreement and an investment of around USD 550 Million.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
 English
Join our community to interact with posts!